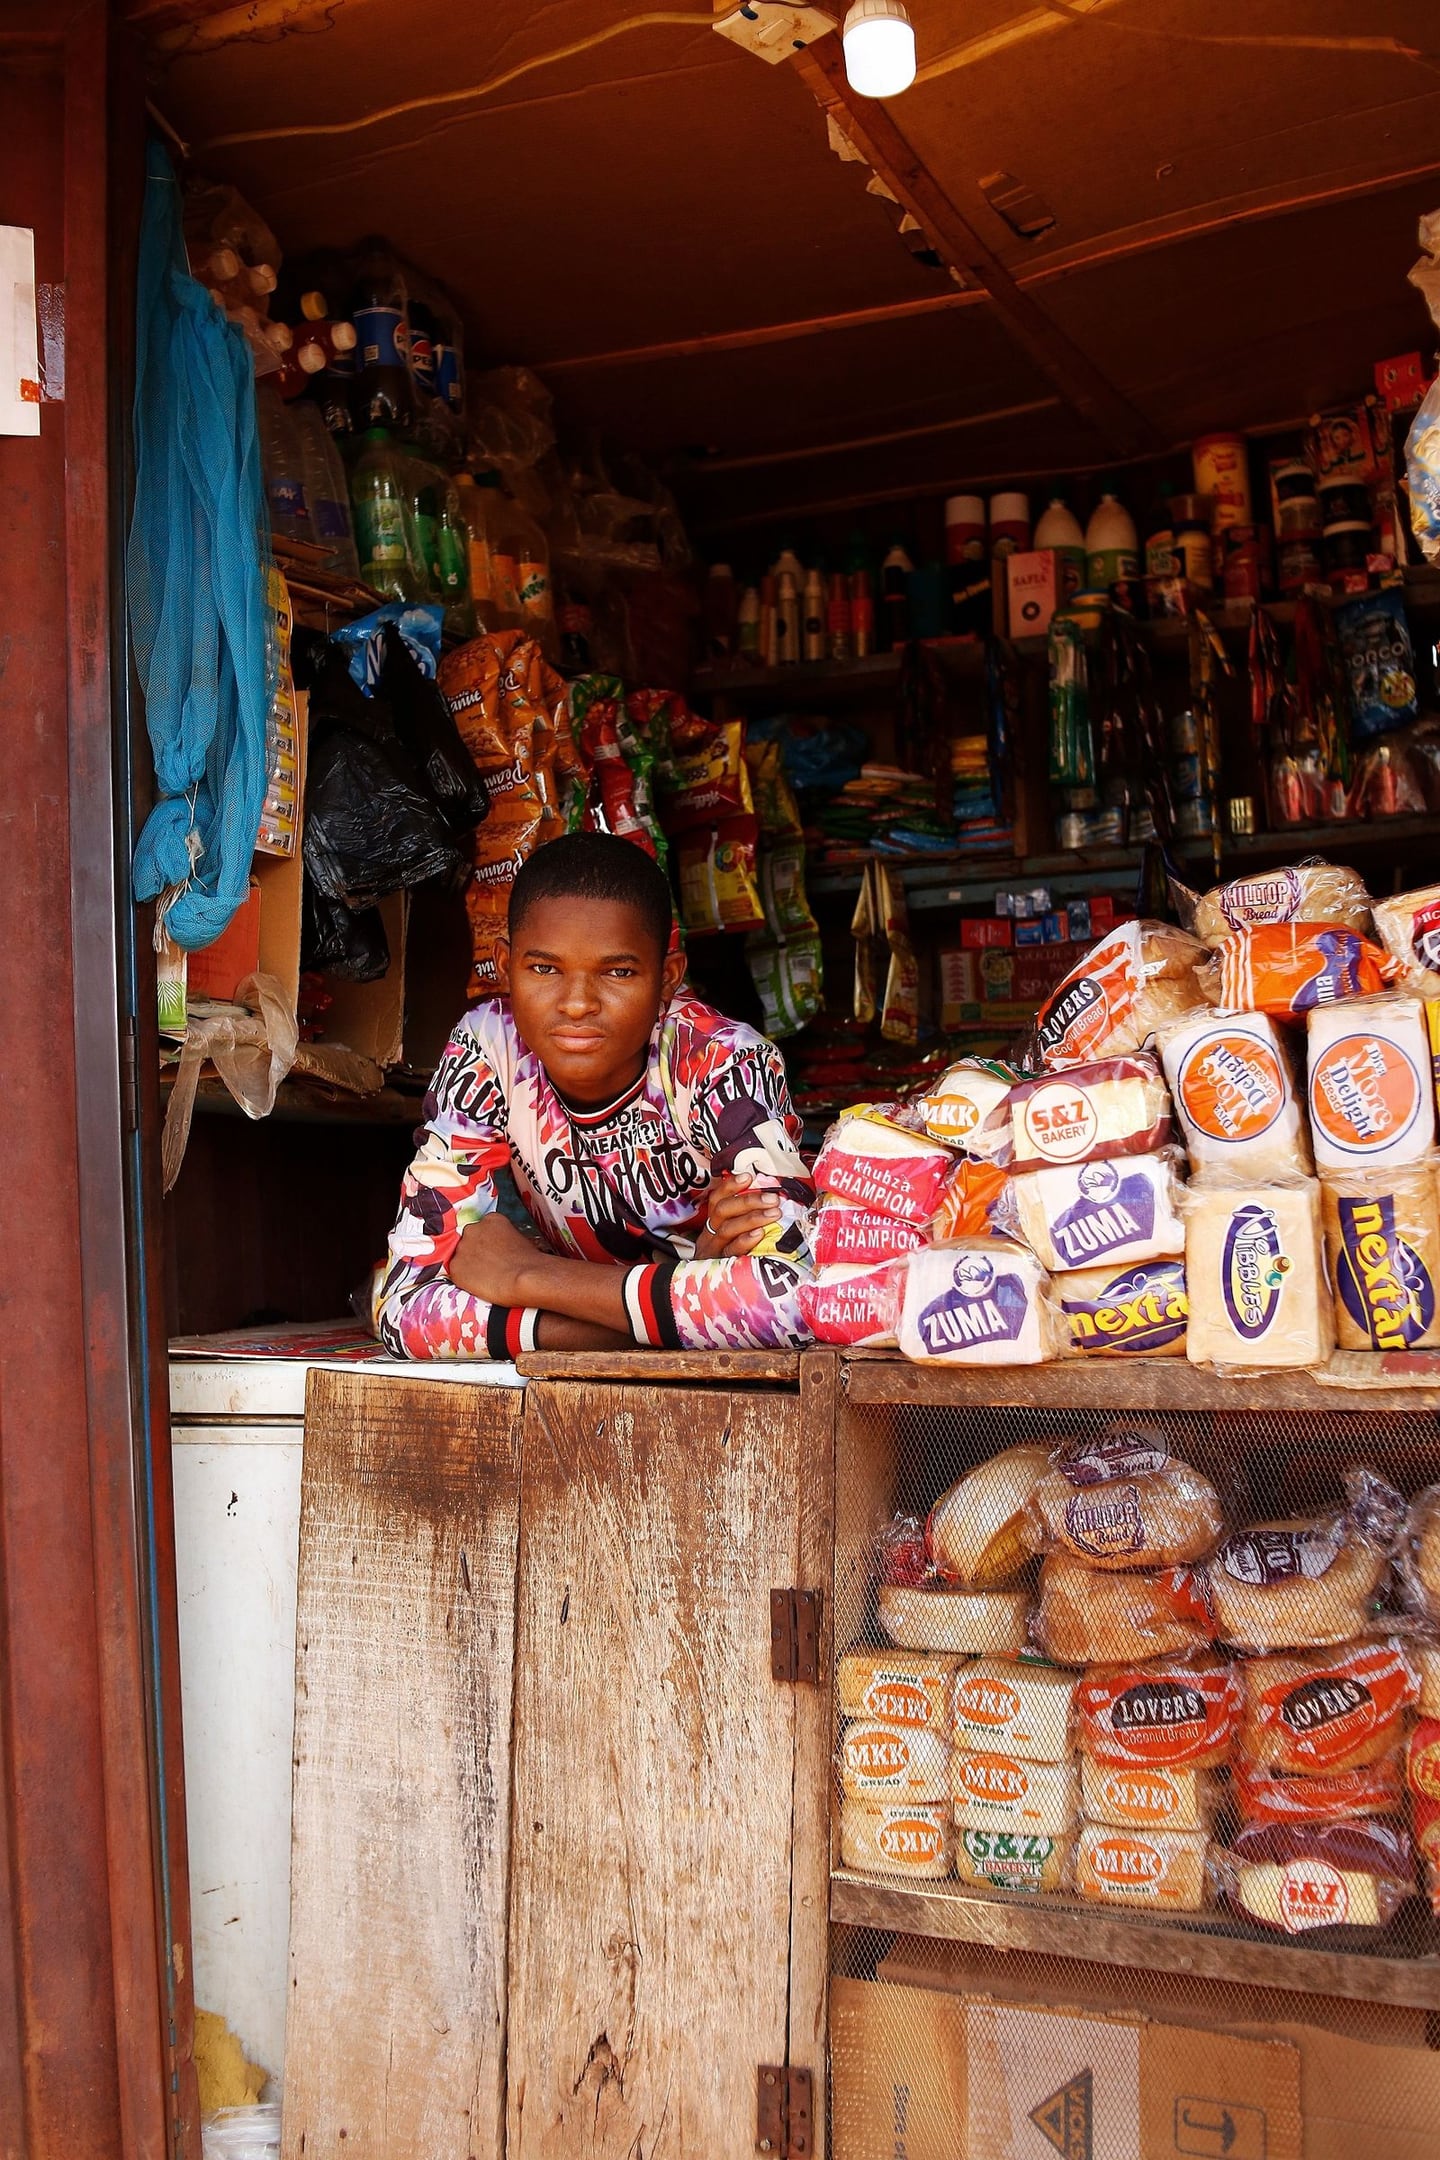
The biggest tax change for small traders this year is a number. From 1 July 2026 the annual turnover at which a Ugandan business must register for VAT is UGX 300 million, double the UGX 150 million that applied before. The change came through the Value Added Tax (Amendment) Act, 2026, one of the tax laws assented to on 18 May 2026 and in force from the start of the financial year. If you run a shop, a restaurant, a pharmacy or a workshop with sales somewhere between those two figures, this quarter is the time to decide what to do about it.
The rule as URA now states it
URA's VAT page puts the registration test in two ways. You must apply for registration if your taxable turnover exceeds, or is expected to exceed, UGX 75,000,000 in any period of three consecutive calendar months, which URA describes as one quarter of the annual threshold of UGX 300,000,000 in any twelve months. Once you cross the line, the application has to be lodged within 20 days from the end of the period in which the obligation arose.
The standard rate is unchanged at 18%. Exports, medicines manufactured in Uganda and cereals grown and milled in Uganda are zero-rated, while unprocessed foodstuffs, education, passenger transport and health and life insurance are among the exempt supplies. A business that only sells exempt goods does not need to register.
For a registered business, the monthly routine is also unchanged: file the VAT return within 15 days after the end of the month and pay any VAT due within the same 15 days. URA notes that EFRIS supports pre-filled returns, so a business issuing e-receipts is mostly cross-checking figures rather than typing them.
Why the threshold moved
Reporting in the Daily Monitor on the change cited URA data that by June 2024 there were 36,417 VAT-registered taxpayers, 90 percent of them very small businesses contributing only about 3 percent of VAT revenue, many of them filing nil returns month after month while carrying the cost of compliance. Parliament's stated aim was to let URA concentrate on larger taxpayers and relieve small firms of the monthly burden. The measure was projected to raise UGX 349 billion in the 2026/27 budget framework.
If you are below UGX 300 million and registered
You have a choice, not an obligation. According to the Monitor's report, businesses below the new threshold may deregister from VAT from 1 July 2026 by filing an online application through the URA portal, and approval depends on URA reviewing your historical records to confirm you qualify.
Before you apply, weigh the trade-off. Deregistering ends the monthly return, but you lose the ability to claim input VAT on your purchases. A trader who buys mostly from VAT-registered wholesalers and sells to businesses that want a tax invoice may be better off staying in. A trader selling to walk-in customers who never ask for a tax invoice usually is not.
Two things do not go away when you deregister. First, EFRIS obligations continue if your sector is one of the twelve gazetted for e-invoicing regardless of VAT status. Second, your income tax obligations continue as before.
If you are above UGX 300 million and not registered
Then nothing has changed in your favour, and the penalty for failing to register is severe: URA states it as double the tax payable from the end of the application window until you register. Count your sales honestly over the last twelve months and the last three months. If either test is met, apply now rather than wait for URA's EFRIS data to make the point for you.
If you stay registered, mind the deadlines
URA's VAT page sets out the cost of slipping: late filing attracts the greater of UGX 200,000 or interest at 2% compounded for the time the return is outstanding, and late payment attracts 2% compounded per month on the unpaid amount. Poor record-keeping can be penalised at double the tax payable for the period.
What to do this quarter
- Pull your sales for July, August and September 2026 and for the twelve months to 30 September. Compare them with UGX 75 million and UGX 300 million.
- If you are under both figures and registered, list your main suppliers and ask whether losing input VAT would cost more than the monthly return saves you.
- If you are over either figure and unregistered, apply within 20 days of the month in which you crossed.
- Whatever you decide, keep issuing compliant receipts. The threshold changed; the record-keeping rules did not.
Tax rules change at the start of every financial year in Uganda. This one is unusual in that it takes a monthly chore away from tens of thousands of small businesses. Make sure the decision you take about it is a deliberate one.
Sources
- https://www.ura.go.ug/en/domestic-taxes/value-added-tax-vat/
- https://www.monitor.co.ug/uganda/business/prosper/vat-threshold-doubled-to-shs300m-what-changes-for-small-businesses--5553596
- https://www.ey.com/en_gl/technical/tax-alerts/uganda-issues-tax-amendment-acts-for-2026
- https://ura.go.ug/en/dt-faqs/
Run the whole business from one login.
Point of sale, stock, CRM, accounting free in every plan, payroll and Kit AI. Start on the web today and add the till, the phone app and the desktop app as you grow.
No card needed · 14-day trial